Business Owners
How to Get a Mortgage in Nashville, Tennessee When You're Self-Employed
Dale Corley · · 8 min read
More homes are coming on the market around Nashville, and that gives self-employed buyers room to negotiate. Redfin’s newest metro report puts Nashville among the five big metros with the biggest jump in new listings, up 9.1% from a year ago.
Your paperwork decides how much of that you can buy, and the right paperwork can show more income than your tax return does. Send me your last two years of returns and 12 months of bank statements, and I’ll tell you which route gets you the best deal. I’m a mortgage broker, so I shop your loan across hundreds of lenders and you don’t have to.
Key takeaways
- I look at your tax returns first, including a one-year option. If they show enough income, a regular loan is usually the cheapest route.
- If write-offs shrink your profit on paper, 12 months of bank statements can show what you really bring in.
- A regular loan goes up to $1,029,250 in Davidson County and four nearby counties, so many Nashville-area buyers don’t need a jumbo loan.
- More listings give you room to ask the seller for a lower price or a credit.
- I shop your loan across hundreds of lenders so you don’t have to.
On this page: How it works · Why returns look low · One-year returns · Bank statement loans · Loan limit · Monthly cost · Moving to Tennessee · Nuances · Whiz Advice
How do I get a mortgage in Nashville if I’m self-employed?
You prove your income with the right documents, and I pick the route that costs you the least. There are two main routes, and I always check the first one first.
- Tax returns. The standard route. If your returns show enough income, it usually costs less.
- Bank statements. If write-offs shrink your profit on paper, 12 months of deposits can show what you really bring in.
My self-employed mortgage guide covers the basics that apply in every state.
Why does my tax return show less than I earn?
Because a smart tax return is built to lower your income. Write-offs for equipment, vehicles, a home office and travel cut your taxable profit, and that is what your accountant is paid to do. The lender then uses the lower number to decide how much you can borrow.
Here is an example. Say your business deposits $342,000 over 12 months, and after write-offs your return shows $84,000 of profit. On paper that is $7,000 a month, even though $28,500 a month came in. A lender who reads only the return sees the smaller number. A bank statement loan reads the deposits. Example only, not a quote.
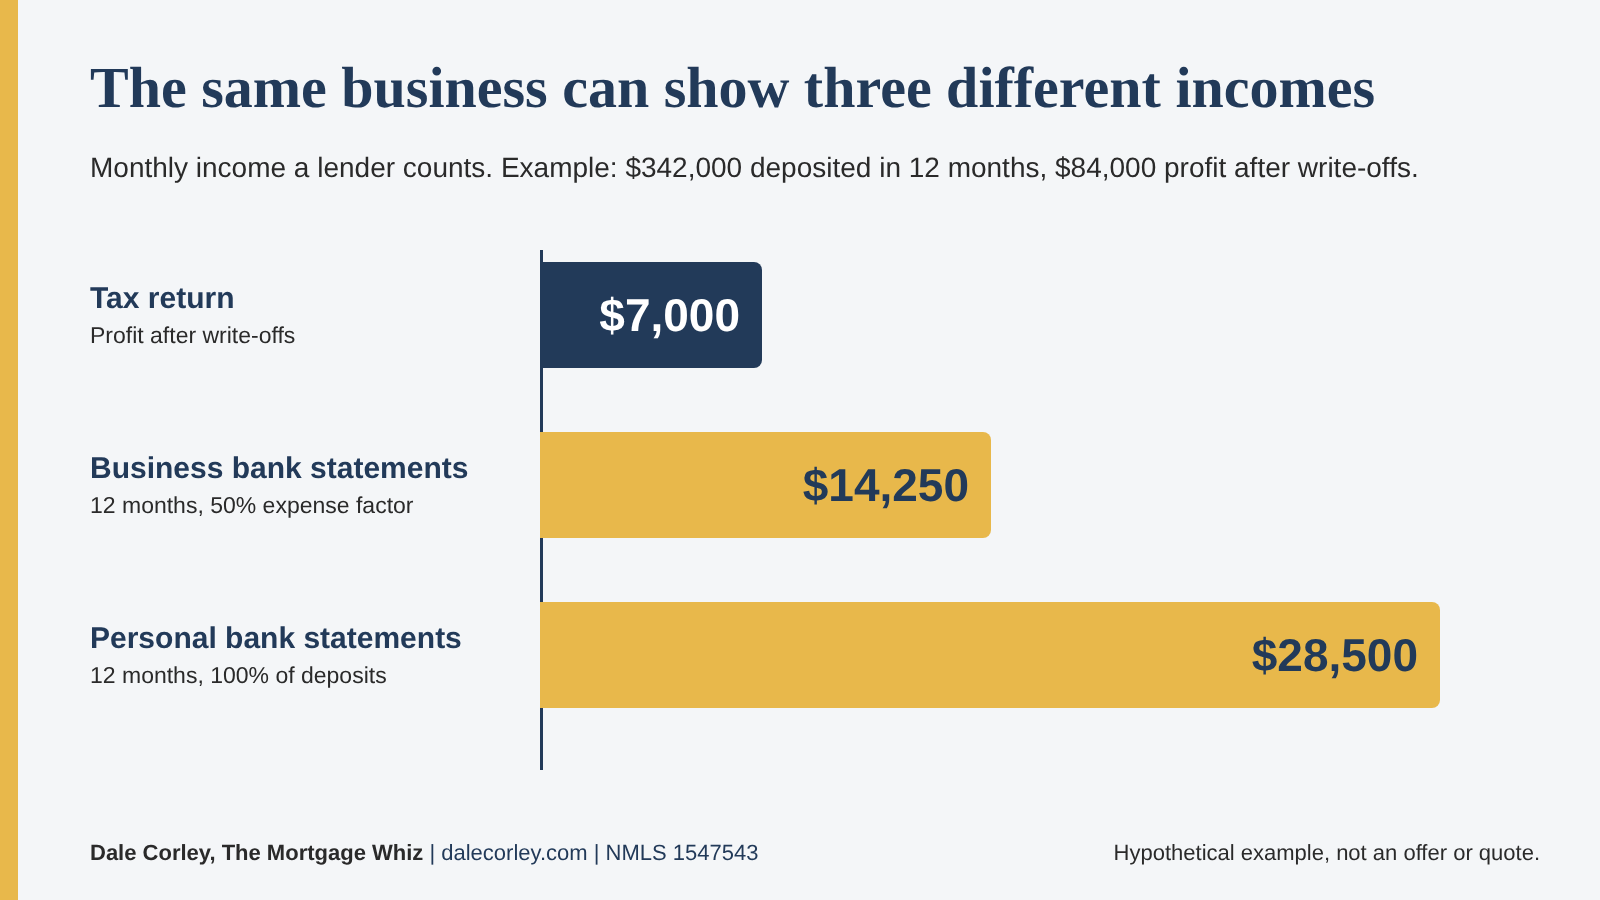
Caption: monthly income counted from the same hypothetical business three ways. Business statements use a 50% expense factor. Example only.
Can I use just one year of tax returns?
Sometimes, and it’s where I look first. Fannie Mae and Freddie Mac both allow one year of tax returns when the business has been open at least five years. Fannie Mae also requires 25% ownership for those five years. Some write-offs, like depreciation, can be added back to your income, which can raise the number a lender uses.
If the returns show enough income, a regular loan is typically the cheapest route. I move to bank statements only when the returns fall short.
How does a bank statement loan work?
It swaps your tax returns for your bank statements. Here is the process.
- You send 12 months of statements. Personal or business, one account. Twelve months is all I need.
- I count the deposits. Personal statements count in full. Business statements have a share taken out for expenses.
- I shop it. I enter your scenario into my loan search system and compare hundreds of lenders.
- Underwriting reviews the file. If a condition looks wrong, I push back before I ask you for more.
- You close. Clean paperwork keeps the file moving.
Here is how the two kinds of statements count, using the example above:
| Statements used | Share of deposits counted | Monthly income used |
|---|---|---|
| Personal account | 100% | $28,500 |
| Business account, 50% expense factor | 50% | $14,250 |
Most lenders call these non-QM (non-traditional) loans. A Qualified Mortgage, or QM, is the CFPB’s category for a loan with safer features that make it more likely you can afford it. A non-QM (non-traditional) loan sits outside that box but still has to meet the federal ability-to-repay rule. It just proves income with different documents. Because the lender takes on more risk, in my experience the rate typically runs about 1% to 2% higher than a traditional loan, and it varies by file and market. In my own pricing this September and October, bank statement rates have been close to regular loan rates.
My bank statement loan guide and bank statement loan page cover credit score, down payment and reserves.
How much can I borrow before I need a jumbo loan?
In Davidson County the regular loan limit for 2026 is $1,029,250, according to the Federal Housing Finance Agency (FHFA). Williamson, Rutherford, Sumner and Wilson counties have the same limit. The standard limit for most of the country is $832,750, so Nashville gets about $196,500 more room.
The limit applies to the loan, not the price. With 10% down, your loan stays under $1,029,250 on a home priced up to about $1.14 million. Above the limit, a loan is called a jumbo loan. My high-balance conforming loan page and jumbo loan page cover each side of the limit.
What does a Nashville-area home cost per month?
Here are five example prices with 10% down. I use the Freddie Mac average for a 30-year fixed loan, 7.18% as of November 5, 2026, for every row so you can compare prices and not loan types. The payment is principal and interest only, which is the loan payment before taxes, insurance and mortgage insurance. These are round example prices, not Nashville medians. Example only, not a quote.
| Home price | 10% down | Loan amount | Principal and interest | Which side of the limit |
|---|---|---|---|---|
| $500,000 | $50,000 | $450,000 | $3,048 | Regular loan |
| $650,000 | $65,000 | $585,000 | $3,963 | Regular loan |
| $850,000 | $85,000 | $765,000 | $5,182 | Regular loan |
| $1,100,000 | $110,000 | $990,000 | $6,707 | Regular loan |
| $1,250,000 | $125,000 | $1,125,000 | $7,621 | Jumbo loan |
Redfin also reports that Nashville’s median sale price was 3.3% lower than a year ago in the four weeks ending October 25, one of the biggest drops among large metros. That is room to ask for a lower price or a seller credit, which is money the seller pays toward your closing costs.
What if my business is in another state or I just moved to Tennessee?
That is rarely a problem. A short letter of explanation that the business continues is usually enough, and there is no minimum time at your new address. Consultants and manufacturers are easier to document than trades with local customers, like plumbing.
One thing does trip people up, and it’s a rental or second home they left behind. Say you’re moving from another state and still own a rental there. You leave it off the application because it’s in a different state and a different county. Every property turns up in the lender’s checks, and the added payment can push your debt-to-income ratio over the limit late in the process. Put every property on the application on day one. This is an example, not a real client.
What nuances do most loan officers miss?
They miss the small things that stall a self-employed file late. Here are the ones I see most.
| What most people think | What I see | Why it matters |
|---|---|---|
| ”I should use my business account.” | Personal statements count 100% of deposits, and all account holders must be on the loan. Business statements have a share taken out for expenses. | One account can qualify you for much more than the other. |
| ”More months of statements are safer.” | Twelve months is all I need. | Twelve months is much easier on you. |
| ”I need a letter from my accountant.” | An experienced bank statement loan officer knows how to clear that condition. | Call me before you chase your accountant. |
| ”Any account will do.” | One business and one account, and the business name must match the statements exactly. | A mismatch can stall a file late. |
I fight the underwriter before I fight the borrower. If a condition looks wrong, I push back first.
Whiz Advice
Here is how I would play it in the Nashville area:
- Get pre-approved before you tour. Most people find the house first. I would rather know your number before you fall in love with one.
- Send me your returns and your statements together. I price both routes and tell you which one saves you more.
- Keep your deposits in one account. Twelve clean months are easy to document. Money bouncing between accounts is not.
- Ask for dollars, not a percent. “$15,000 toward closing costs” is clearer than “3%,” and it is easier for a seller to say yes to.
- Check your price against the loan limit before you offer. I can run your price both ways, as a regular loan and as a jumbo loan, so you see the difference first.
Why use a mortgage broker?
I shop your rates with other lenders, so you don’t have to.
Shopping for a mortgage on your own means applying again and again, sending the same documents over and over, and waiting on every quote. I do that part for you, with one application.
What you get when you work with me:
- One application, one credit pull. I compare hundreds of lenders for you, including most of the big banks and big lenders.
- More loan options than one bank can offer. VA, jumbo, bank statement, DSCR and other non-QM (non-traditional) loans. A single bank can only offer its own programs.
- Pricing from a large wholesale platform. I’m a mortgage broker with NEXA Lending, the largest brokerage in the country by loan officer headcount. In my experience, that volume helps me get wholesale pricing that many banks can’t match.
- Help when your file isn’t standard. If you’re self-employed, have unusual income or have a lower credit score, I know which lenders fit.
- A real person from start to finish. I answer your questions and make sure your application is accurate, so there are no surprises later.
How do you get ready to buy in the Nashville area?
Here is what you can do this week:
- Gather two years of tax returns and 12 months of bank statements. Send both, and I’ll tell you which route fits.
- Pay your credit cards down. Aim for under 10% of your limits, and no higher than 30%, so your debt-to-income ratio stays healthy.
- Get pre-approved before you shop. It tells you your price range and makes your offer stronger.
- Put everything on the application and tell me your concerns up front. That includes any property you own in another state.
- Send me your numbers. My job is to find the loan program that fits your situation best and make sure the application is accurate. The bank statement income calculator is a good place to start.
Pick your next step:
- Ready to get pre-approved? Start your loan application. It’s the fastest way to find out what you can buy.
- Have a one-of-a-kind situation? Book a 15-minute call and we’ll talk it through.
- Just have a question? Email me at [email protected] with your scenario, and I’ll write back.
I’m a mortgage broker with NEXA Lending, and I work with borrowers all over Tennessee, including Nashville. As a broker, I can shop your loan across hundreds of lenders instead of being stuck with one bank’s programs. Programs, rates and approval depend on your full file. This is educational and not tax or legal advice.
Sources: Redfin, U.S. Home-Sale Prices Just Fell for the First Time in 3 Years, Oct 29, 2026, FHFA, 2026 conforming loan limits by county, Freddie Mac, Primary Mortgage Market Survey, Nov 5, 2026, CFPB, what is a Qualified Mortgage.
Dale Corley | NMLS #1547543 | Licensed in CA, CO, TX, FL, GA, NC, SC, TN, VA | This is not a commitment to lend.