Business Owner Mortgage
Why Tax Write-Offs Shrink Your Mortgage, and How to Still Qualify
Dale Corley · · 8 min read
If you write off a lot on your taxes, you can still get a mortgage. You just have to know which income the lender is going to count, because it usually isn’t the income you think you make.
Last reviewed October 20, 2026
I have this conversation with business owners all the time. They had a great year, their CPA did a great job, and then a loan officer tells them they “only” make a fraction of what hits their bank account. Nobody did anything wrong. The tax return and the mortgage are just measuring two different things.
Key takeaways
- A regular mortgage counts the profit on your tax return after write-offs, not your deposits.
- Lenders can add back some write-offs that never cost you cash, like depreciation.
- If the returns still fall short, a bank statement loan counts 12 months of deposits instead.
- In the example below, the same owner qualifies on $16,000 a month with tax returns and $30,000 a month with bank statements.
- The best time to sort this out is before you house hunt, not after you’re under contract.
Why it happens · What lenders add back · The example · Bank statement option · The Edge · Next steps
Why do tax write-offs lower my mortgage income?
Because a regular lender starts with the profit on your tax return, and every write-off comes off that number first. Fannie Mae’s Selling Guide tells lenders to begin with the net profit on your Schedule C, the business page of your personal return, and adjust from there.
Your CPA’s job is to make your taxable income as small as the law allows. A lender’s job is to prove you can afford the payment. Those two goals pull in opposite directions, and the write-offs are where they collide.
What write-offs can a lender add back?
Lenders add back write-offs that didn’t take cash out of your pocket. Fannie Mae lists depreciation, depletion, amortization, casualty losses and business use of your home as items lenders add back to Schedule C income. Depreciation is the big one for most owners. It’s the tax deduction for a truck, equipment or a building wearing out over time.
What doesn’t come back: real expenses you paid with real money. Payroll, rent, software, travel, the marketing budget. Those are business costs, and the lender treats them that way. Fannie Mae also has lenders subtract any meals and entertainment exclusion you report.
How big is the difference in real numbers?
Here’s an example, not a quote. A business owner wants to buy a $1.5 million home. Their business deposits $720,000 over the last 12 months. After a long list of legitimate write-offs, their tax returns show $168,000 a year of net profit, and $24,000 of the write-offs was depreciation.
| How the lender counts income | Yearly | Monthly |
|---|---|---|
| Net profit on the tax return | $168,000 | $14,000 |
| Tax return plus the depreciation add-back | $192,000 | $16,000 |
| Bank statements, 50% expense factor on $720,000 of deposits | $360,000 | $30,000 |
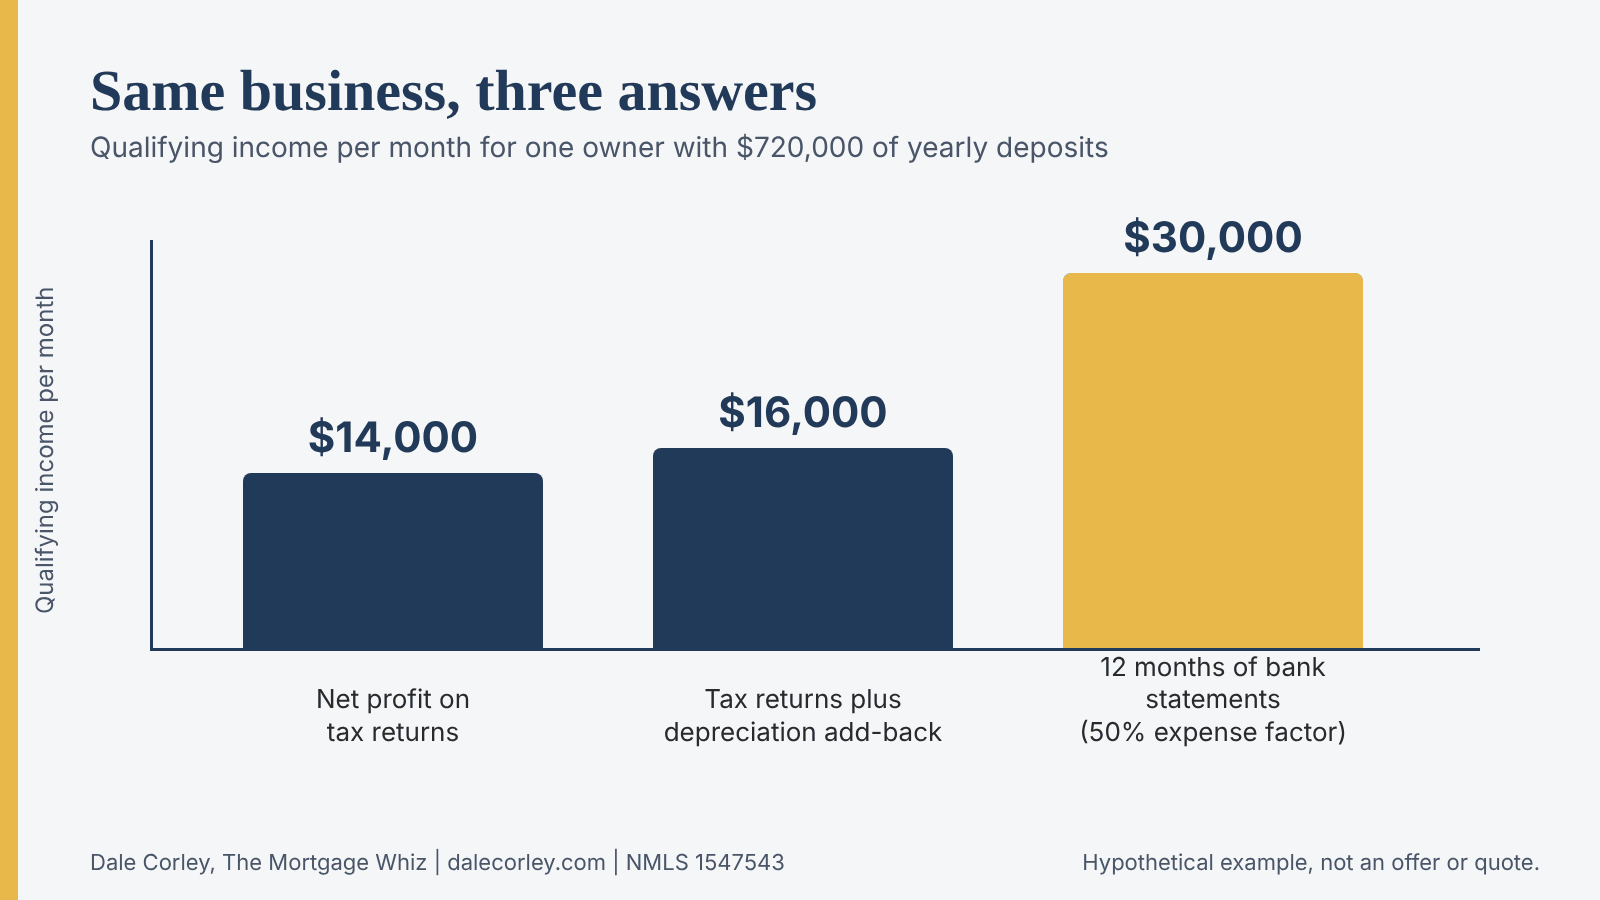 Same owner, same year. How the income gets counted changes the answer by $14,000 a month.
Same business. Same year. The bank statement method counts almost twice the income. That gap is usually the difference between “you don’t qualify for that house” and “let’s write the offer.”
Should I always start with the tax returns?
Yes. I read your returns first, every time, because the cheapest loan that works is the one you want. A regular loan with tax returns usually has the better rate. Freddie Mac can sometimes accept just one year of tax returns when the business has been open five years or more, which helps if last year was your strong year.
If the returns plus add-backs get you where you need to be, we’re done. Bank statements only come into the picture when they don’t.
What if my tax returns still don’t qualify me?
Then I look at a bank statement loan, which qualifies you on 12 months of personal or business bank statements instead of your tax returns. Business deposits are usually counted after an expense factor, often around 50%, which stands in for your business costs. Personal account deposits can sometimes count in full.
Most lenders call these non-QM (non-traditional) loans. A Qualified Mortgage, or QM, is the CFPB’s category for a loan with safer features that make it more likely you can afford it. A non-QM (non-traditional) loan sits outside that box but still has to meet the federal ability-to-repay rule. It just proves income with different documents.
Because the lender takes on more risk, in my experience the rate typically runs about 1% to 2% higher than a traditional loan, and it varies by file and market. Plenty of owners are happy to make that trade, because their write-offs save them more in taxes than the rate costs them. I walk through the full program in my bank statement loan guide, and the bank statement income calculator runs your own deposits.
What nuances do most loan officers miss?
| What most people think | What I see | Why it matters |
|---|---|---|
| You need 24 months of bank statements | 12 months of personal or business statements does the job | Half the paperwork, and your most recent year counts |
| Self-employed means go straight to a bank statement loan | Tax returns first, including Freddie Mac’s one-year option | The regular loan is usually cheaper when it works |
| You’ll need a CPA letter up front | Most files never need one when the standard expense factor qualifies | Chasing a CPA letter on day one stalls files for no reason |
| Business and personal accounts count the same | Personal deposits can count in full, business deposits get an expense factor | Picking the right account can change your income a lot |
| Any of your accounts will do | It’s one business and one account, and the names must match exactly | A mismatch shows up late and slows everything down |
The Edge
Here’s what your CPA probably hasn’t told you. The lender’s math is decided by the returns you’ve already filed, so the time to plan is a year before you buy, not the week you find the house.
If you know you’re buying in the next year, you have a real choice. You can keep taking every write-off and plan on a bank statement loan. Or you can talk with your CPA about whether reporting more income this year makes a regular loan work. This is educational, not tax advice, and neither answer is right for everyone. The point is to make it a decision instead of a surprise.
A pitfall I see: the pre-approval that wasn’t
This is a pattern, not a real client. A buyer gets a pre-approval from someone who pulled credit and wrote down the income the buyer said out loud. Nobody read the tax returns. Three weeks into the contract, underwriting reads them, the write-offs leave too little income, and the loan gets declined.
The buyer calls me days from closing. Sometimes I can move the file to a bank statement program fast, and speed is one of the things that separates a broker from a big bank. But it’s a rescue, and no one can promise the original closing date. Ten minutes with your returns on day one prevents the whole thing.
How do you get ready this week?
- Pull your last two tax returns and find the net profit on each one.
- Download 12 months of statements from the business account your income actually runs through.
- Get your credit cards low, ideally under 10% of the limits and no higher than 30%, so your debt-to-income stays healthy.
- Get pre-approved before you shop. Most buyers do it backwards and find the house first.
- Tell me your concerns up front and leave nothing off the application. Surprises late are what kill files.
My job is to help you find the loan program that fits your situation best and make sure the application is accurate from the start. If you want more on the first steps, read What Is a Bank Statement Loan and How Does It Work?.
Why use a mortgage broker?
Let hundreds of lenders compete for your loan. You fill out one application.
Shopping for a mortgage on your own means applying again and again, sending the same documents over and over, and waiting on every quote. I do that part for you.
Here’s how it works:
- Tell me your goals. I review them and structure your loan.
- I shop it. I enter your scenario into my loan search system. It checks hundreds of lenders, including most of the big banks and big lenders, and sorts them by rate, APR (the yearly cost of the loan, including fees), monthly payment or total cost.
- You get the best deal. If the lowest rate is your goal, I sort by rate, find the lender with the lowest rate at the moment you’re ready to lock, and lock it. Typically 350 or more lenders sit underneath with higher rates.
One application. One set of documents. Hundreds of lenders working for your business. I also make sure your application is accurate, so there are no surprises later.
Pick your next step
- Ready to get pre-approved: start your application
- Your situation is one of a kind: book a 15-minute call
- Just a question or a scenario: email [email protected]
I’m a mortgage broker with NEXA Lending, and I work with borrowers in all nine states where I’m licensed (CA, CO, TX, FL, GA, NC, SC, TN, VA). As a broker, I can shop your loan across hundreds of lenders instead of being stuck with one bank’s programs. Programs, rates and approval depend on your full file.
Sources: Fannie Mae Selling Guide B3-3.3-03, Income or Loss Reported on IRS Form 1040, Schedule C, Freddie Mac, Income Calculator FAQ (one year of tax data for a business in existence five or more years), CFPB, What Is a Qualified Mortgage?.
Dale Corley | NMLS #1547543 | Licensed in CA, CO, TX, FL, GA, NC, SC, TN, VA | This is not a commitment to lend.