Cash-out refinance
- Their low-rate first mortgage
- Paid off and gone
- New first mortgage
- $1,050,000 ($450,000 payoff plus $600,000 cash)
- Cash for the project
- $600,000, all on day one
$1,050,000
Debt at today’s rate
For homeowners with a low rate to protect
Borrow against your home for a remodel, a business or your next property without touching your first mortgage.

Why this loan exists
Millions of homeowners locked in rates around 3% before 2022. Many of them now own a home worth far more than they paid, and life has changed. The family grew, the business needs cash, or the kitchen is twenty years old. The old answer was a cash-out refinance, but that means trading your low rate for today’s rate on the whole balance.
A HELOC leaves your first mortgage alone. It sits behind it as a second loan, so your low rate and your payment stay exactly where they are. You only pay today’s rate on the money you actually borrow, and only once you borrow it.
Your equity is the part of your home you own outright: its value minus what you owe. Lenders measure it with the CLTV, short for combined loan-to-value. That is every loan on the home added together, divided by its value. If your home is worth $1 million and you owe $500,000, your CLTV is 50%. The CFPB explains how a line of credit works if you want the government’s plain version.
I still check the other options first. If you need one lump sum and want a fixed payment, a home equity loan may fit better. If your current rate is high anyway, a cash-out refinance can make more sense. I lay all three side by side before you apply.
Side by side
Take a couple with a $1.6 million home near Charlotte. They owe $450,000 on a loan they locked in at a low rate in 2021, and they need $600,000 for a pool and an outdoor kitchen. Both paths get them the money. The difference is how much of their debt ends up at today’s rate.
$1,050,000
Debt at today’s rate
Only what they draw
Debt at today’s rate
Same $600,000 for the project. The HELOC keeps $450,000 at their old rate and starts at $0 borrowed.
HELOC or home equity loan
Both are second mortgages that sit behind your first loan. The difference is how you get the money and how the rate works. <a href="https://www.consumerfinance.gov/ask-cfpb/what-is-the-difference-between-a-home-equity-loan-and-a-home-equity-line-of-credit-heloc-en-247/" target="_blank" rel="noopener noreferrer">The CFPB compares them</a> the same way.
Choose this if you’ll spend the money over time, like a remodel paid in stages, or want a cushion you may never use.
Choose this if you need all the money at once and want a payment that never changes.
Bottom line
Both keep your first mortgage in place, and both can qualify you with bank statements, a profit and loss statement (P&L) or other non-traditional income if you’re self-employed. If you’d rather qualify that way for a whole new loan, see my bank statement loan page. To compare a refinance against keeping your current loan, try the refinance calculator.
Real math
The size of your line comes down to three things: what your home is worth, what you still owe and your credit score. Here is how those play out for three homeowners who want to keep their first mortgage.
Scenario 1 · A remodel without losing a low rate
They owe $600,000 on a loan from 2021 and want to redo the kitchen and add a screened porch. Their credit score is 720.
The numbers
The result
$400,000
Credit line they could open
Their equity supports $468,000, but most programs cap lines at $400,000 for credit under 760. That is still plenty for the remodel.
Watch for: Lines above $400,000 usually need 760+ credit and stop at 80% of value. Raising their score wouldn’t help them here, because 80% leaves only $360,000.
Scenario 2 · Cash for the next property
He owns a rental in Tampa free and clear and wants cash for the down payment on his next one. His credit score is 780.
The numbers
The result
$675,000
Credit line he could open
With no mortgage on the rental, the whole 75% is his to use. He draws the down payment for the next purchase and leaves the rest open for repairs.
Watch for: Only some programs lend on rentals, and the limit is lower than on a primary home. If he wants a fixed payment instead, a home equity loan on a rental goes up to 80%.
Scenario 3 · A business owner’s safety net
She runs a design firm in Raleigh, owes $350,000 on her home and has a 780 credit score. She wants a cushion for slow months that costs nothing until she uses it.
The numbers
The result
$450,000
Credit line she could open
Her 780 score opens the larger tier, so she can go past $400,000 at 80% of value. She qualifies with 12 months of bank statements instead of tax returns full of write-offs.
Watch for: Business account deposits usually count at about half, to allow for expenses, while personal account deposits count in full.
Get my options
Three quick taps and an optional note. I read every one myself and reply, usually the same day.
What are you looking to do?
How do you earn most of your income?
When would you like to buy or close?
Optional. A sentence or two about your situation helps me come to our call prepared.
Where should I reach you?
Your answers are already filled in below, so I’ll know your situation before we talk.
Rather just talk?
Run your numbers
Enter your home’s value and what you still owe. The calculator applies the limits typical across the programs I can access and shows the line you could likely open.
Credit line you could likely open
$0
Based on limits typical across the HELOC programs I can access: up to 89% of value on a primary home, 80% in Texas, about 75% on rentals, and 80% for lines over $400,000 (760+ credit, up to $1M).
Who this is for
HELOC borrowers have one thing in common: real equity in their home and a good reason not to refinance.
Your family outgrew the house, but you don’t want to move. A HELOC pays for the addition while you stay right where you are.
Your first mortgage rate is likely far below today’s rates. A HELOC lets you use your equity without giving that up.
Restaurant owners, contractors and professional practices use a line for equipment, a second location or a cash cushion. You can qualify with bank statements instead of tax returns.
Pull cash from a rental or your own home for the next down payment, then pay the line down when the property sells or refinances.
Builders bill as the work gets done. A line lets you pay each invoice as it arrives, so you only pay interest on what’s been spent.
Need your down payment before your old home sells? A line on your current home can bridge the gap, and you pay it off when the sale closes.
How a HELOC works
During the draw period, often 5 to 10 years, you can borrow, pay back and borrow again, up to your limit. Most programs only require interest on what you’ve drawn during this time. When the draw period ends, the line closes and what you owe turns into a regular loan you pay off over the repayment period.
The rate on most HELOCs is variable. It moves with the prime rate, so your payment can rise or fall. That is why a HELOC fits money you plan to pay back in a few years, and why I also show you the fixed home equity loan before you choose.
The life of a HELOC
By state law, Texas homeowners can borrow up to 80% of value counting the first mortgage, only on the home they live in. Each draw must be at least $4,000.
On many programs, lines up to about $250,000 to $400,000 can use an automated valuation (a computer estimate of your home’s value) instead of a full appraisal. That saves time and money.
Requirements
These are the typical terms across the HELOC and home equity programs I can access.
How much of your home’s value you can borrow against
Options vary by state, and not every program is available everywhere. One HELOC per property at a time. There is no monthly mortgage insurance on a HELOC.
Checklist
Recently funded
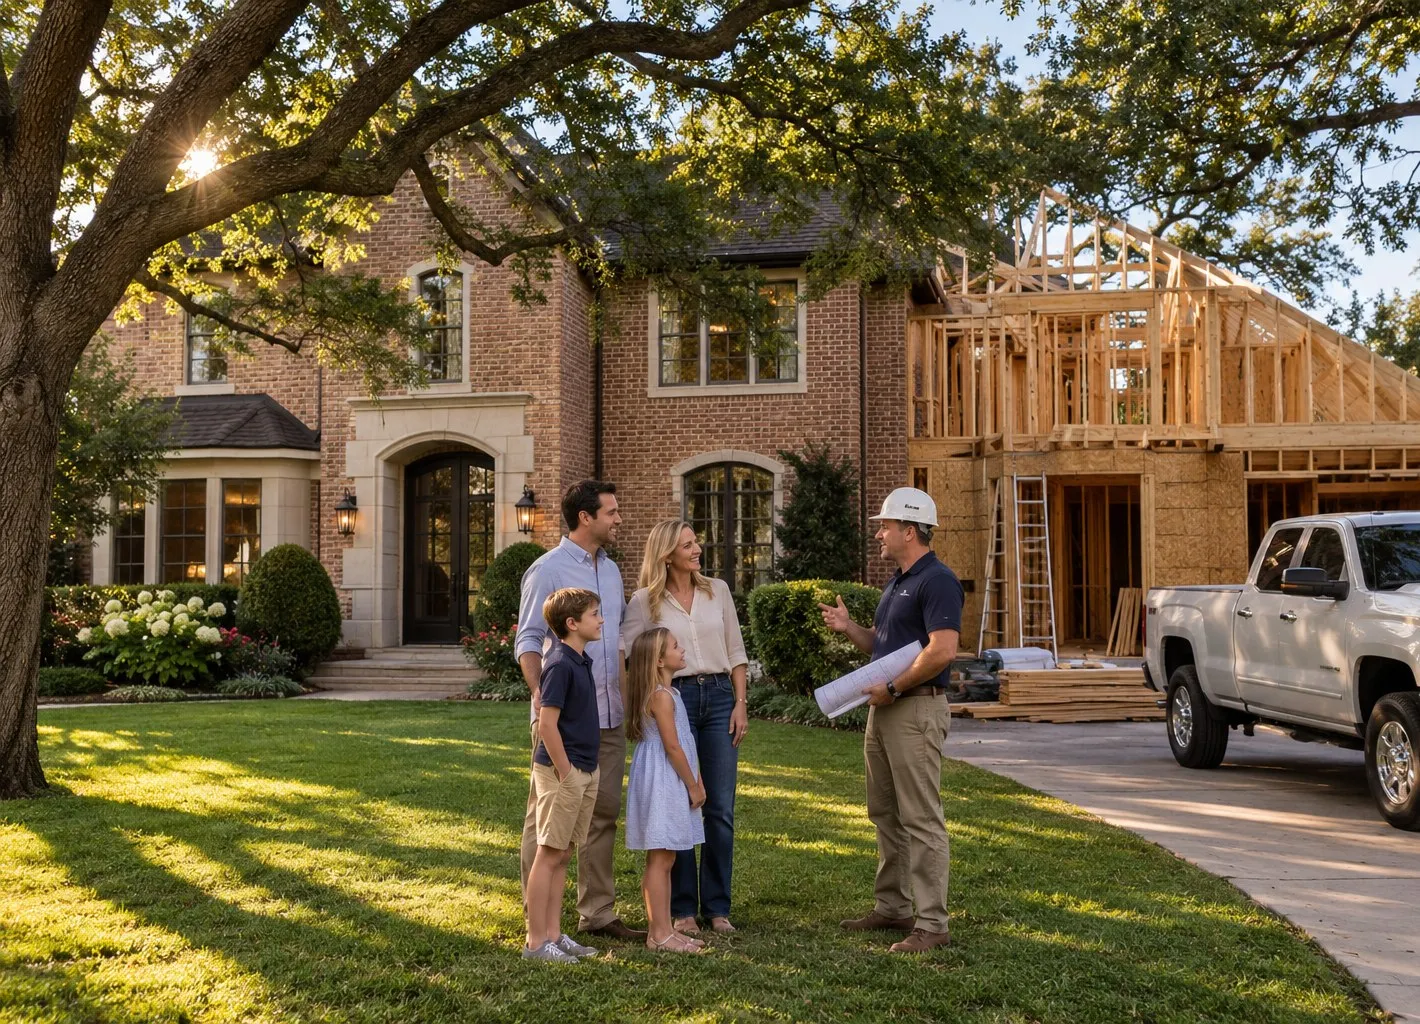
I helped this couple buy their home in Southlake in 2020 for $950,000. They locked in a 3.125% rate and fell in love with the neighborhood and the schools. By 2026 the home was worth about $1.4 million, and their family had grown out of it.
They didn’t want to move. Selling meant giving up the neighborhood, the kids’ school and that 3.125% rate, then buying again at today’s prices and rates. So they hired an architect and a builder and planned an addition with an extra room and a theater upgrade. The budget came to about $750,000.
A cash-out refinance would have paid off their low-rate loan and put more than $1.1 million at today’s rate. Instead, we kept their first mortgage, with about $370,000 left on it, and opened a $750,000 HELOC behind it. Their credit was over 760, and the two loans together came to 80% of the home’s value, right at the Texas limit.
The line pays the builder in stages as each invoice comes in, so they only pay interest on work that is done, and their savings stay in the bank. Once the work wraps up, after about a year, the home is expected to appraise at about $2.5 million. They never had to move or give up that 3.125% rate.
A real loan I closed. Details that could identify the borrower are left out.
Watch-outs
A HELOC is simple when it’s set up right. These are the problems I see most, and each one is easy to avoid if we plan ahead.
Lenders approve a line based on your income and credit when you apply. Open it while business is strong, before a slow season, a job change or a big purchase on credit.
Most lenders won’t open a line on a home that’s for sale. If you need equity for your next down payment, open the line before you list.
Most HELOC rates rise and fall with the prime rate. Plan your budget with room to spare, or ask me about a fixed home equity loan instead.
Most HELOCs are based on what your home is worth today, not what it will be worth once the work is done. Size your project to today’s value, and pay down the line once the new value is set.
A line on your home is cheap money for things that build value: a remodel, a business or a property. Using it for vacations and cars turns your house into a credit card.
FAQ
A HELOC is a credit line you draw from as needed, usually at a variable rate, and you pay interest only on what you use. A home equity loan gives you one lump sum at closing with a fixed rate and a fixed payment. Both are second mortgages, so your first mortgage stays in place either way.
No. A HELOC is a separate loan that sits behind your first mortgage. Your first loan’s rate, balance and payment stay exactly the same. That is the main reason homeowners with low rates choose a HELOC over a cash-out refinance.
Take up to 89% of your home’s value and subtract what you owe on your first mortgage. Lines over $400,000 usually need 760+ credit and stop at 80% of value, and Texas caps home equity borrowing at 80%. The calculator above does the math for you.
Yes. Many of the programs I access accept 12 months of bank statements or a P&L in place of tax returns, the same way a bank statement loan works. That matters for business owners whose returns show less income because of write-offs.
Yes, on select programs, usually up to about 75% to 80% of the rental’s value. A fixed home equity loan on a rental can also qualify on the rent itself, using a DSCR (debt service coverage ratio) check instead of your personal income. Texas HELOCs are only allowed on the home you live in, by state law.
It depends on the size of the line. Many programs use an automated valuation for lines up to about $250,000 to $400,000. Larger lines, including most over $400,000, need a full appraisal with someone walking through the home.
If your first mortgage rate is lower than today’s rates, a HELOC usually wins because you keep that rate. If your current rate is high, or you want one loan and one fixed payment, a cash-out refinance can make more sense.
Google reviews
“Need a good mortgage person? Use Dale. He made the process a breeze. We knew where we stood the entire time, through his electronic process and tracker. Nothing happened we did not expect. Dale checked in often and responded 100% to every email, call, text, and very promptly. There were no last minute requests, no “oh wait underwriting needs this now”, no surprises. Dale made a typically very stressful and nerve wracking process, easily understood and made it just a normal business transaction. Use Dale!”
Keep reading
Sources
Program terms are typical ranges across the programs I can access and can change. Not a commitment to lend. Dale Corley, mortgage broker, NMLS #1547543.
Start an application and send your latest mortgage statement. I’ll show you what a HELOC, a home equity loan and a cash-out refinance would each do for you. Then we pick the one that keeps the most money in your pocket.
Apply Now