VA Loans
VA Loan Limit in Virginia Beach and Hampton Roads (2026)
Dale Corley · · 8 min read
Homes in Virginia Beach are taking longer to sell. In October, a resale single-family home took a median of 32 days to sell, up from 17 days in September, according to REIN MLS data (the local listing service’s numbers) compiled by Hampton Roads Real Estate Ramblings. That extra time gives a veteran with a ready VA pre-approval room to negotiate instead of rushing.
So what’s the VA loan limit here? The short answer: with full entitlement, there isn’t one. I’m a mortgage broker, so I shop your VA loan across hundreds of lenders and you don’t have to. Send me your price range and your Certificate of Eligibility, and I’ll show you what you can buy with $0 down.
Key takeaways
- With full entitlement, VA sets no loan limit anywhere in Virginia.
- The county limit matters only if you still have a VA loan on another home: $832,750 in Hampton Roads and $1,249,125 in most of Northern Virginia for 2026.
- Moving here on orders and keeping your last home? You can still buy, usually with a small down payment above the zero-down amount.
- If your down payment on a second VA loan is already close to 5%, going to 5% cuts the funding fee from 3.3% to 1.5%.
- I shop hundreds of lenders for your VA loan, so you don’t have to.
The limit · Full entitlement · $0 down example · Moving on orders · Northern Virginia · The market · Disabled veterans · Whiz Advice
What is the VA loan limit in Virginia Beach?
VA doesn’t set one if you have full entitlement. Your price is capped by what you can afford and what the home appraises for, not by a county number. Your lender still sets its own maximum loan size. Entitlement is the part of your loan VA backs, which is why lenders can lend with no down payment.
The county limit only comes back when part of your entitlement is still tied up in another VA loan. VA uses the same county limits FHFA sets for conforming conventional loans. Here’s Virginia for 2026:
| Where in Virginia | 2026 county limit (one-unit home) |
|---|---|
| Virginia Beach, Norfolk, Chesapeake, Portsmouth, Suffolk, Hampton, Newport News | $832,750 |
| Arlington, Fairfax, Loudoun, Prince William, Stafford, Spotsylvania, Alexandria and 10 more Northern Virginia areas | $1,249,125 |
| Madison County | $1,209,750 |
| The rest of Virginia, including Richmond | $832,750 |
FHFA set these limits on November 25, 2025, and it has announced each new year’s limits in the last week of November for the past four years. If you’re buying in early 2027 with a VA loan still open, I’ll recheck the new figure for you.
What does full entitlement mean?
If you’ve never used VA, or you sold your last VA home and paid off the loan, your full benefit is back. Either way, your budget comes down to income and the appraisal.
If you still owe on a VA loan for a home you kept, you have what’s called remaining (sometimes partial) entitlement. That’s the case in Hampton Roads that needs real math, and I walk through it below. My post on VA loan benefits for million-dollar homes covers the big-home side of the benefit.
What does a $470,000 Virginia Beach home look like with a VA loan?
Here’s an example, not a quote. A first-time VA buyer with full entitlement buys at the October median price of $470,000. VA charges a one-time funding fee, and on a first VA loan it’s 2.15% with less than 5% down, 1.5% with 5% or more and 1.25% with 10% or more. You can roll it into the loan.
| $0 down | 5% down | 10% down | |
|---|---|---|---|
| Down payment | $0 | $23,500 | $47,000 |
| Funding fee | $10,105 (2.15%) | $6,698 (1.5%) | $5,288 (1.25%) |
| Loan with the fee added | $480,105 | $453,198 | $428,288 |
| Principal and interest, 30-year VA at a 6.875% example rate | $3,154 | $2,977 | $2,814 |
Taxes and homeowners insurance come on top of these payments. No column has monthly mortgage insurance, because VA loans don’t charge it.
What if you’re moving to Hampton Roads and keeping a home with a VA loan?
You can still use your VA benefit. You’ll usually just need a small down payment on the part above your zero-down amount. That’s good news if you’re coming to Naval Station Norfolk, NAS Oceana or Joint Base Langley-Eustis and want to rent out your last home instead of selling it.
Here’s how VA’s math works, with an example. Say you kept a home with a $300,000 VA loan. VA backs 25% of a loan, so $75,000 of your entitlement is still in use.
- Start with the county limit. In Chesapeake it’s $832,750. A quarter of that is $208,187.50.
- Subtract what’s in use. $208,187.50 minus $75,000 leaves $133,187.50 of remaining entitlement.
- Find your zero-down amount. Most lenders want VA’s backing plus your down payment to cover 25% of the loan, so multiply by 4. You can borrow up to $532,750 with $0 down, before the funding fee.
- Above that, put down the gap. On a $650,000 home, 25% is $162,500. Subtract your $133,187.50, and you’d put down about $29,313, or 4.5%. Because it’s your second VA loan, the funding fee is 3.3% with under 5% down, 1.5% with 5% or more and 1.25% with 10% or more.
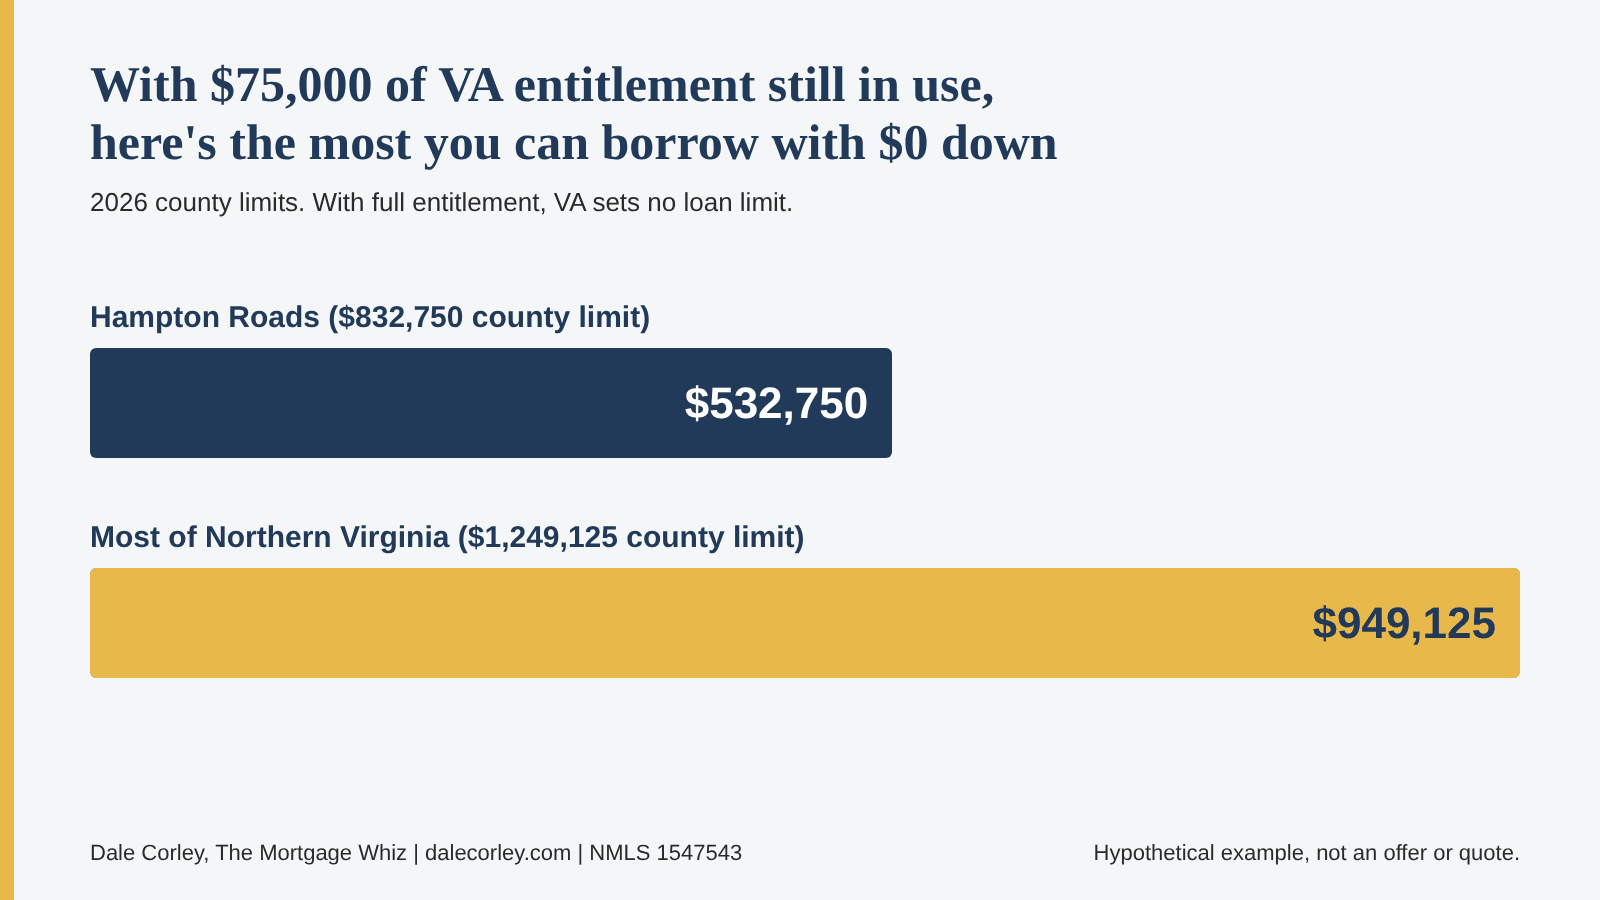 Hypothetical example with $75,000 of entitlement still in use on a past VA loan.
Each lender figures this a bit differently. Your Certificate of Eligibility, the VA document that shows how much entitlement you’ve used, is what I run it against.
How does the math change in Northern Virginia?
The higher county limit gives you more room. In Fairfax, Arlington, Loudoun and the other Northern Virginia areas at $1,249,125, a quarter of the limit is $312,281.25.
A veteran who kept a home with a $300,000 VA loan still has $75,000 of entitlement in use. The remaining entitlement is $237,281.25, so the zero-down amount is $949,125. On a $1,100,000 townhome, 25% is $275,000, and the down payment is about $37,719, or 3.4%.
How fast are Hampton Roads homes selling?
Slower than a month ago, but supply is still tight. Months of supply means how long the current listings would last at today’s pace of sales. A low number means few homes to choose from.
| October 2026, resale single-family homes (excluding waterfront) | Median price | Median days on market | Months of supply |
|---|---|---|---|
| Virginia Beach | $470,000 | 32 | 1.2 |
| Chesapeake | $450,000 | 38 | 1.5 |
| Suffolk | $420,962 | 42 | 2.3 |
| Norfolk | $340,000 | 34 | 1.3 |
| Portsmouth | $299,500 | 34 | 1.3 |
The report credits higher rates and more homes to choose from for the slower pace. It’s one local source, so I watch it month to month.
What should disabled veterans in Virginia know?
Two benefits stack up here. If you get VA compensation for a service-connected disability, you don’t pay the VA funding fee at all, which would take $10,105 off a $470,000 Virginia Beach purchase with $0 down. My VA funding fee post lists everyone who’s exempt.
Virginia adds its own. A veteran rated 100% service-connected, permanent and total, or rated at 100% through individual unemployability and permanent and total, pays no real estate tax on the home they live in and up to one acre, according to the Virginia Department of Veterans Services. You apply with your city or county Commissioner of the Revenue. Because property taxes are part of your monthly payment, the exemption lowers the payment too.
Whiz Advice
- Know your entitlement before you set a budget. Full and remaining entitlement can mean very different price ranges, so settle it before you fall for a house.
- On a second VA loan, look hard at 5% down. In the Chesapeake example, raising the down payment from about $29,313 to $32,500 drops the funding fee from 3.3% to 1.5%. That’s $3,188 more cash to save about $11,220 in fees.
- With homes sitting longer, ask for a credit before a price cut, in dollars. VA puts no limit on what a seller can pay toward normal closing costs, and allows up to 4% of the value in other concessions, like paying your funding fee. “$9,000 toward closing costs” is clearer than a percent, and a credit pays your costs now while a small price cut barely moves the payment.
Why use a mortgage broker?
I shop your rates with other lenders, so you don’t have to.
Shopping for a mortgage on your own means applying again and again, sending the same documents over and over, and waiting on every quote. I do that part for you, with one application.
What you get when you work with me:
- One application, one credit pull. I compare hundreds of lenders for you, including most of the big banks and big lenders.
- More loan options than one bank can offer. VA, jumbo, bank statement, DSCR and other non-QM (non-traditional) loans. A single bank can only offer its own programs.
- Pricing from a large wholesale platform. I’m a mortgage broker with NEXA Lending, the largest brokerage in the country by loan officer headcount. In my experience, that volume helps me get wholesale pricing that many banks can’t match.
- Help when your file isn’t standard. If you’re self-employed, have unusual income or have a lower credit score, I know which lenders fit.
- A real person from start to finish. I answer your questions and make sure your application is accurate, so there are no surprises later.
How do you get ready to buy in Hampton Roads?
Here’s what you can do this week:
- Find your Certificate of Eligibility, or send me your DD-214 or statement of service and I’ll request it.
- List any VA loan you still have, with the original loan amount, so I can figure out your remaining entitlement.
- Get pre-approved before you shop. A pre-approval letter tells sellers you’re ready, and it tells you your price range before you shop.
- Send me the city and the homes you’re watching. I’ll show you the $0 down amount and the payment before you write an offer.
Pick your next step:
- Ready to get pre-approved? Start your loan application. It’s the fastest way to find out what you can buy.
- Moving on orders with a home to keep? Book a 15-minute call and we’ll run your entitlement together.
- Just have a question? Email me at [email protected] with your scenario, and I’ll write back.
I’m a mortgage broker with NEXA Lending, and I work with borrowers all over Virginia, including Virginia Beach and the rest of Hampton Roads. Programs, rates and approval depend on your full file.
Sources: Hampton Roads Real Estate Ramblings, Market Update, November 2, 2026 (REIN MLS data, October 2026), FHFA, 2026 conforming loan limits by county, FHFA, Conforming loan limits, VA, VA home loan limits, VA, Funding fee and closing costs, Virginia Department of Veterans Services, Real estate tax exemption.
Dale Corley | NMLS #1547543 | Licensed in CA, CO, TX, FL, GA, NC, SC, TN, VA | This is not a commitment to lend.